Summary
Paying for assisted living without selling your house is possible through several practical financial strategies. This guide explores six smart options that can help preserve homeownership while managing care costs effectively.
- Rent out your home to generate monthly income that offsets assisted living expenses, though factor in property management fees, maintenance, taxes, and potential vacancy periods
- Access home equity through loans, lines of credit, or reverse mortgages (age 62+), but understand repayment terms and consult a financial advisor before borrowing
- Review existing long-term care insurance policies for coverage details, daily benefit limits, waiting periods, and eligible services
- Combine Veterans benefits, retirement savings, Social Security, pensions, and investment income to build a comprehensive payment plan
- Consult a Missouri elder law attorney about Medicaid planning, trusts, and asset protection strategies, as these require careful consideration of eligibility rules
Moving into assisted living doesn't necessarily mean selling the family home. For many families, keeping the property preserves treasured memories, provides financial flexibility, or allows loved ones to continue living there.
Fortunately, several strategies can help with paying for assisted living without selling your house. From rental income to insurance benefits, understanding your options can help you plan for care without rushing into a property sale.
Rent Your Property for Monthly Income
Renting out your home can generate monthly income to offset assisted living expenses while keeping the property in your family.
This approach may be particularly helpful if the home is in good condition and located in an area with consistent rental demand.
Before renting, consider several expenses:
- Property management fees and tenant-related costs
- Ongoing maintenance, repairs, and property taxes
- Homeowners insurance and potential coverage changes
- Periods when the property may remain vacant
Hiring a property manager can simplify responsibilities, especially when family members live outside the area.
While rental income isn't guaranteed, careful budgeting can make this one of several practical financing senior living options.
Access Home Equity Through Borrowing
Home equity loans and lines of credit may provide funds without requiring an immediate property sale.
Families considering keeping a home while in assisted living should understand how these borrowing options work.
Home Equity Financing Options
- Home Equity Loan: Provides a lump sum secured by the property, typically requiring regular monthly payments.
- Home Equity Line of Credit (HELOC): Allows eligible homeowners to access funds as needed, often with variable interest rates.
- Reverse Mortgage: Allows qualifying homeowners age 62 or older to access home equity. However, the property generally must remain the borrower's primary residence.
A permanent move into assisted living can trigger reverse mortgage repayment. Therefore, this option may not be suitable for someone planning to leave their home permanently.
Discuss borrowing costs, repayment requirements, and potential risks with a qualified financial advisor before making a decision.
Leverage Long-Term Care Insurance Benefits
Existing long-term care insurance may help cover assisted living expenses while preserving homeownership.
Coverage varies by policy, so reviewing the details before moving is important.
Look for:
- Daily or monthly benefit limits
- Waiting periods before payments begin
- Eligibility requirements for receiving benefits
- Covered services and potential exclusions
Some policies may help with room, board, and personal assistance, while others have restrictions.
Contact the insurance provider to confirm coverage and understand the claims process. This can help families compare assisted living payment alternatives without making assumptions about available benefits.
Combine Veterans Benefits With Other Resources
Veterans and surviving spouses may be eligible for VA Aid and Attendance benefits, which provide additional financial assistance to individuals meeting specific service, health, and financial requirements.
These benefits may help offset assisted living costs when combined with other available income.
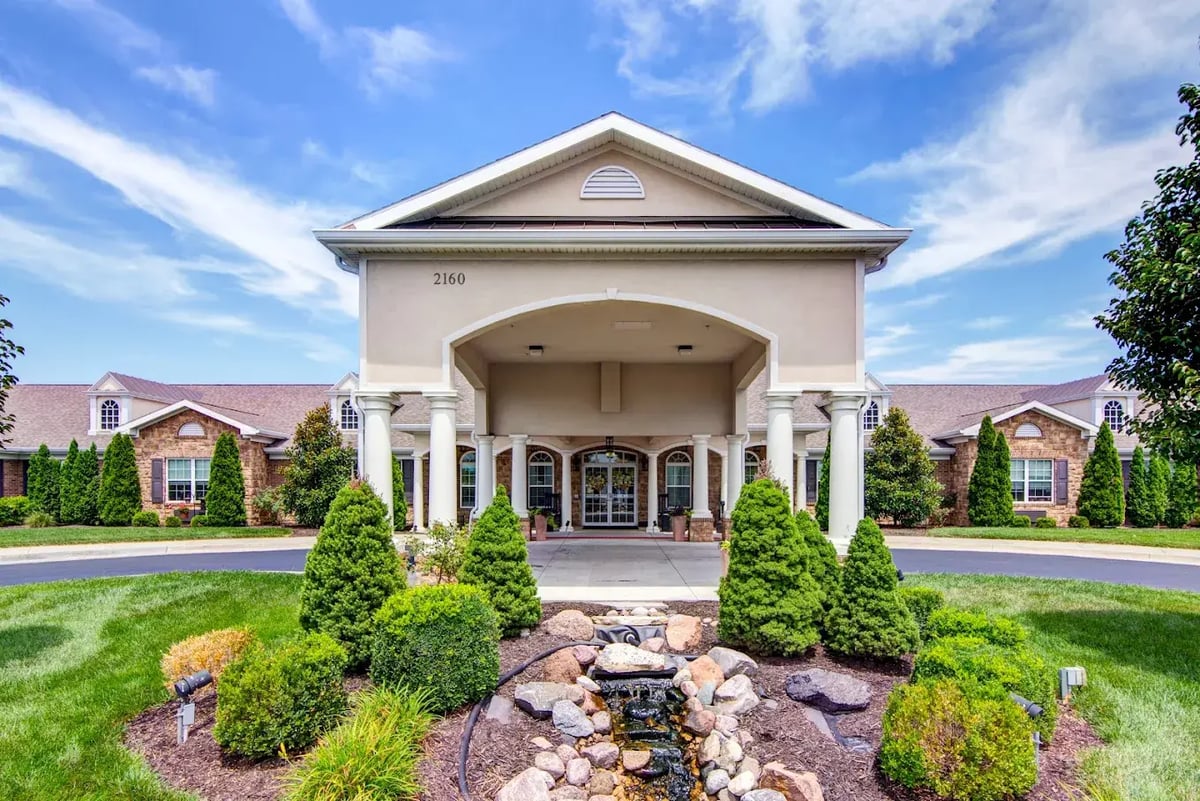
At Addington Place of Lee's Summit, the Military Veterans Program offers exclusive savings for veterans who are eligible. The community also partners with Patriot Angels to help qualifying individuals explore available VA benefits.
Because eligibility and benefit amounts vary, families should verify requirements before incorporating anticipated payments into their budgets.
Use Retirement Savings and Investment Income
Retirement accounts, pensions, Social Security, and investment income can provide additional resources for senior living expenses.
Combining these sources may help families afford senior living without a home sale.
A financial planner can help determine how much income is available and whether retirement withdrawals are sustainable.
Building a Practical Monthly Budget
When comparing current household costs with community living, consider:
- Mortgage payments, utilities, and property maintenance
- Groceries, transportation, and household expenses
- Existing home assistance or personal care costs
- Monthly community fees and additional services
At Addington Place of Lee's Summit in Lee's Summit, MO, Assisted Living includes chef-prepared meals, weekly housekeeping, scheduled transportation, and personalized daily support.
Families can explore available floor plans and pricing to better understand their potential monthly expenses.
Explore Missouri Medicaid Planning and Trusts
Medicaid may help eligible Missouri residents pay for certain long-term care services. However, eligibility, covered services, and participation requirements vary.
A primary residence may receive certain asset protections, depending on ownership, household circumstances, and applicable Medicaid rules.
Some families also consider trusts or other legal arrangements to preserve property. These strategies require careful planning because asset transfers can affect Medicaid eligibility.
Consult a Missouri elder law attorney before changing property ownership or transferring assets. Medicaid estate recovery rules may also apply, so retaining a home doesn't automatically protect it permanently.
Create a Financial Plan That Fits Your Family
The most effective senior living financial strategies often combine multiple resources rather than relying on one payment method.
Start by reviewing available income, homeownership expenses, insurance coverage, and potential benefits. Then compare these resources with the anticipated cost of community living.
Addington Place of Lee's Summit offers a warm, neighborly environment where residents can enjoy familiar routines, homestyle dining, and opportunities for connection while receiving personalized support.
Exploring your financial options early can help your family make informed decisions while preserving flexibility for the future.
Schedule a tour of Addington Place of Lee's Summit today to explore Assisted Living, discuss available pricing, and discover a welcoming community that feels like home.